Two kinds of engagement

Start with the document you need to deliver. A set of annual financial statements and a funding settlement call for different work and different reports.

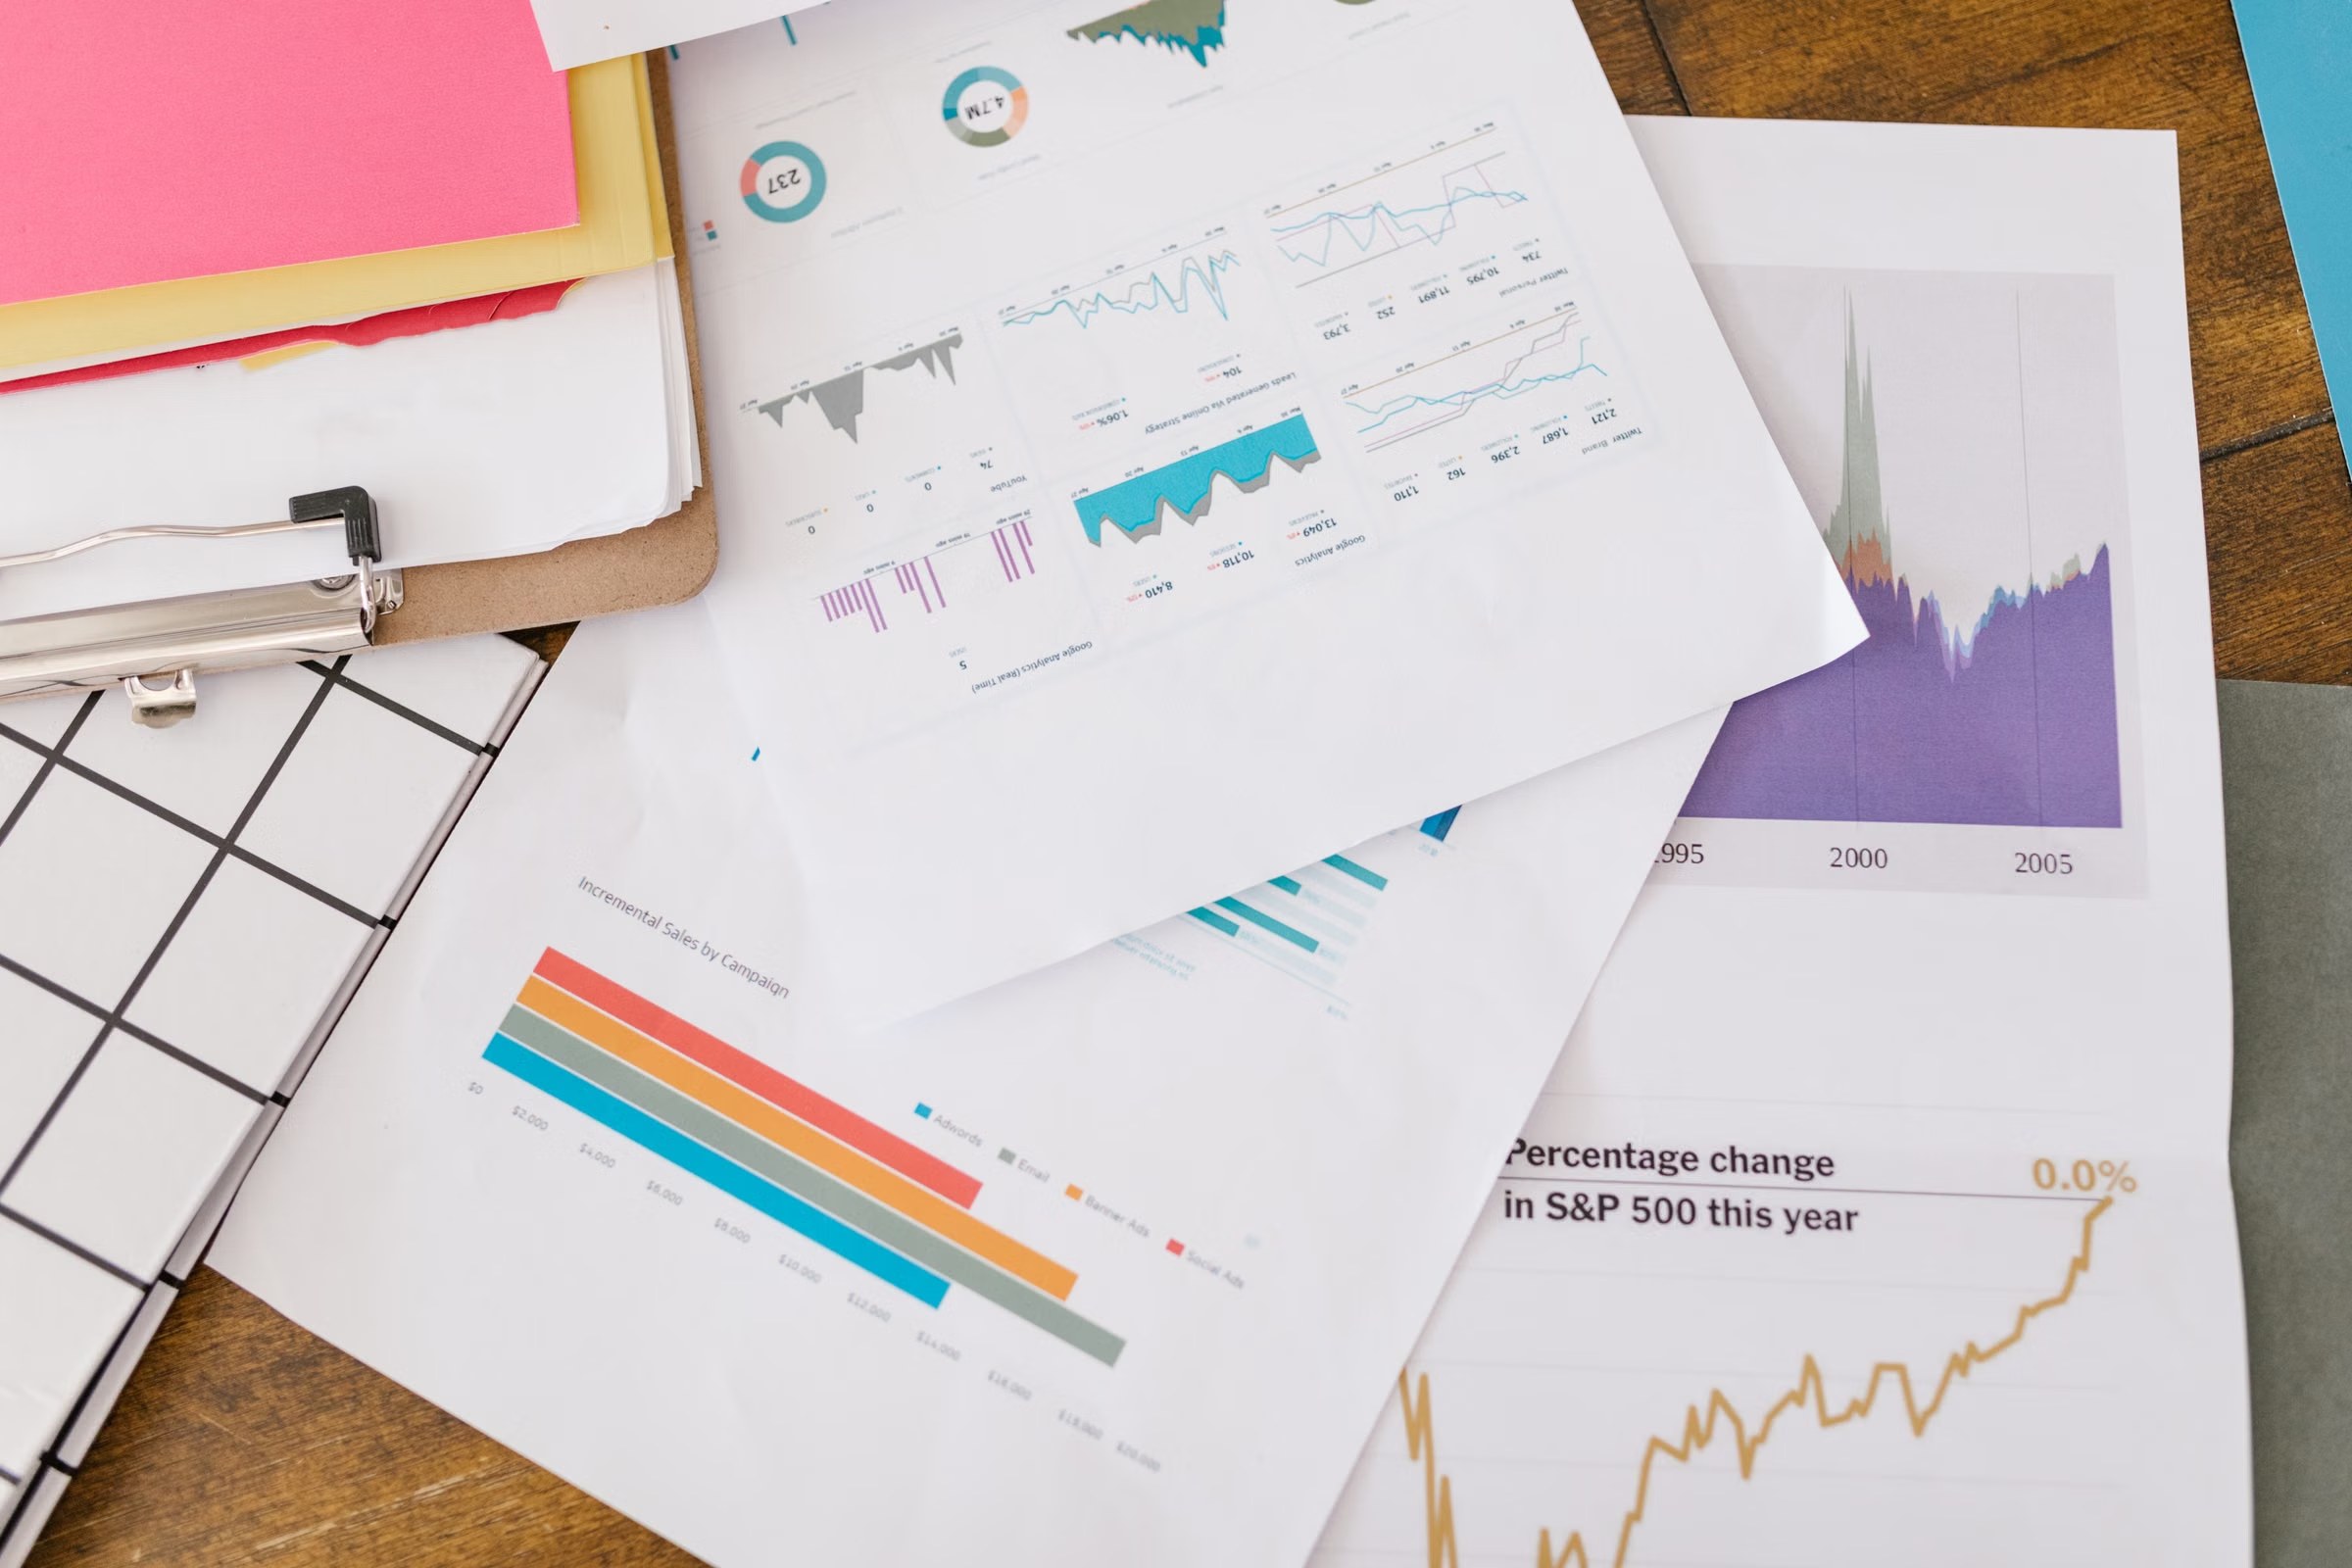
Printed financial charts, notes and stationery spread over a desk.

Statutory audit

A financial statement audit examines accounting information and supporting evidence so the auditor can express an opinion on the statements taken as a whole.

What to prepare
Specify the entity, the financial year, the reporting framework and the date by which the auditor’s report is needed.
What it covers
An auditor’s report on the financial statements within the agreed scope.
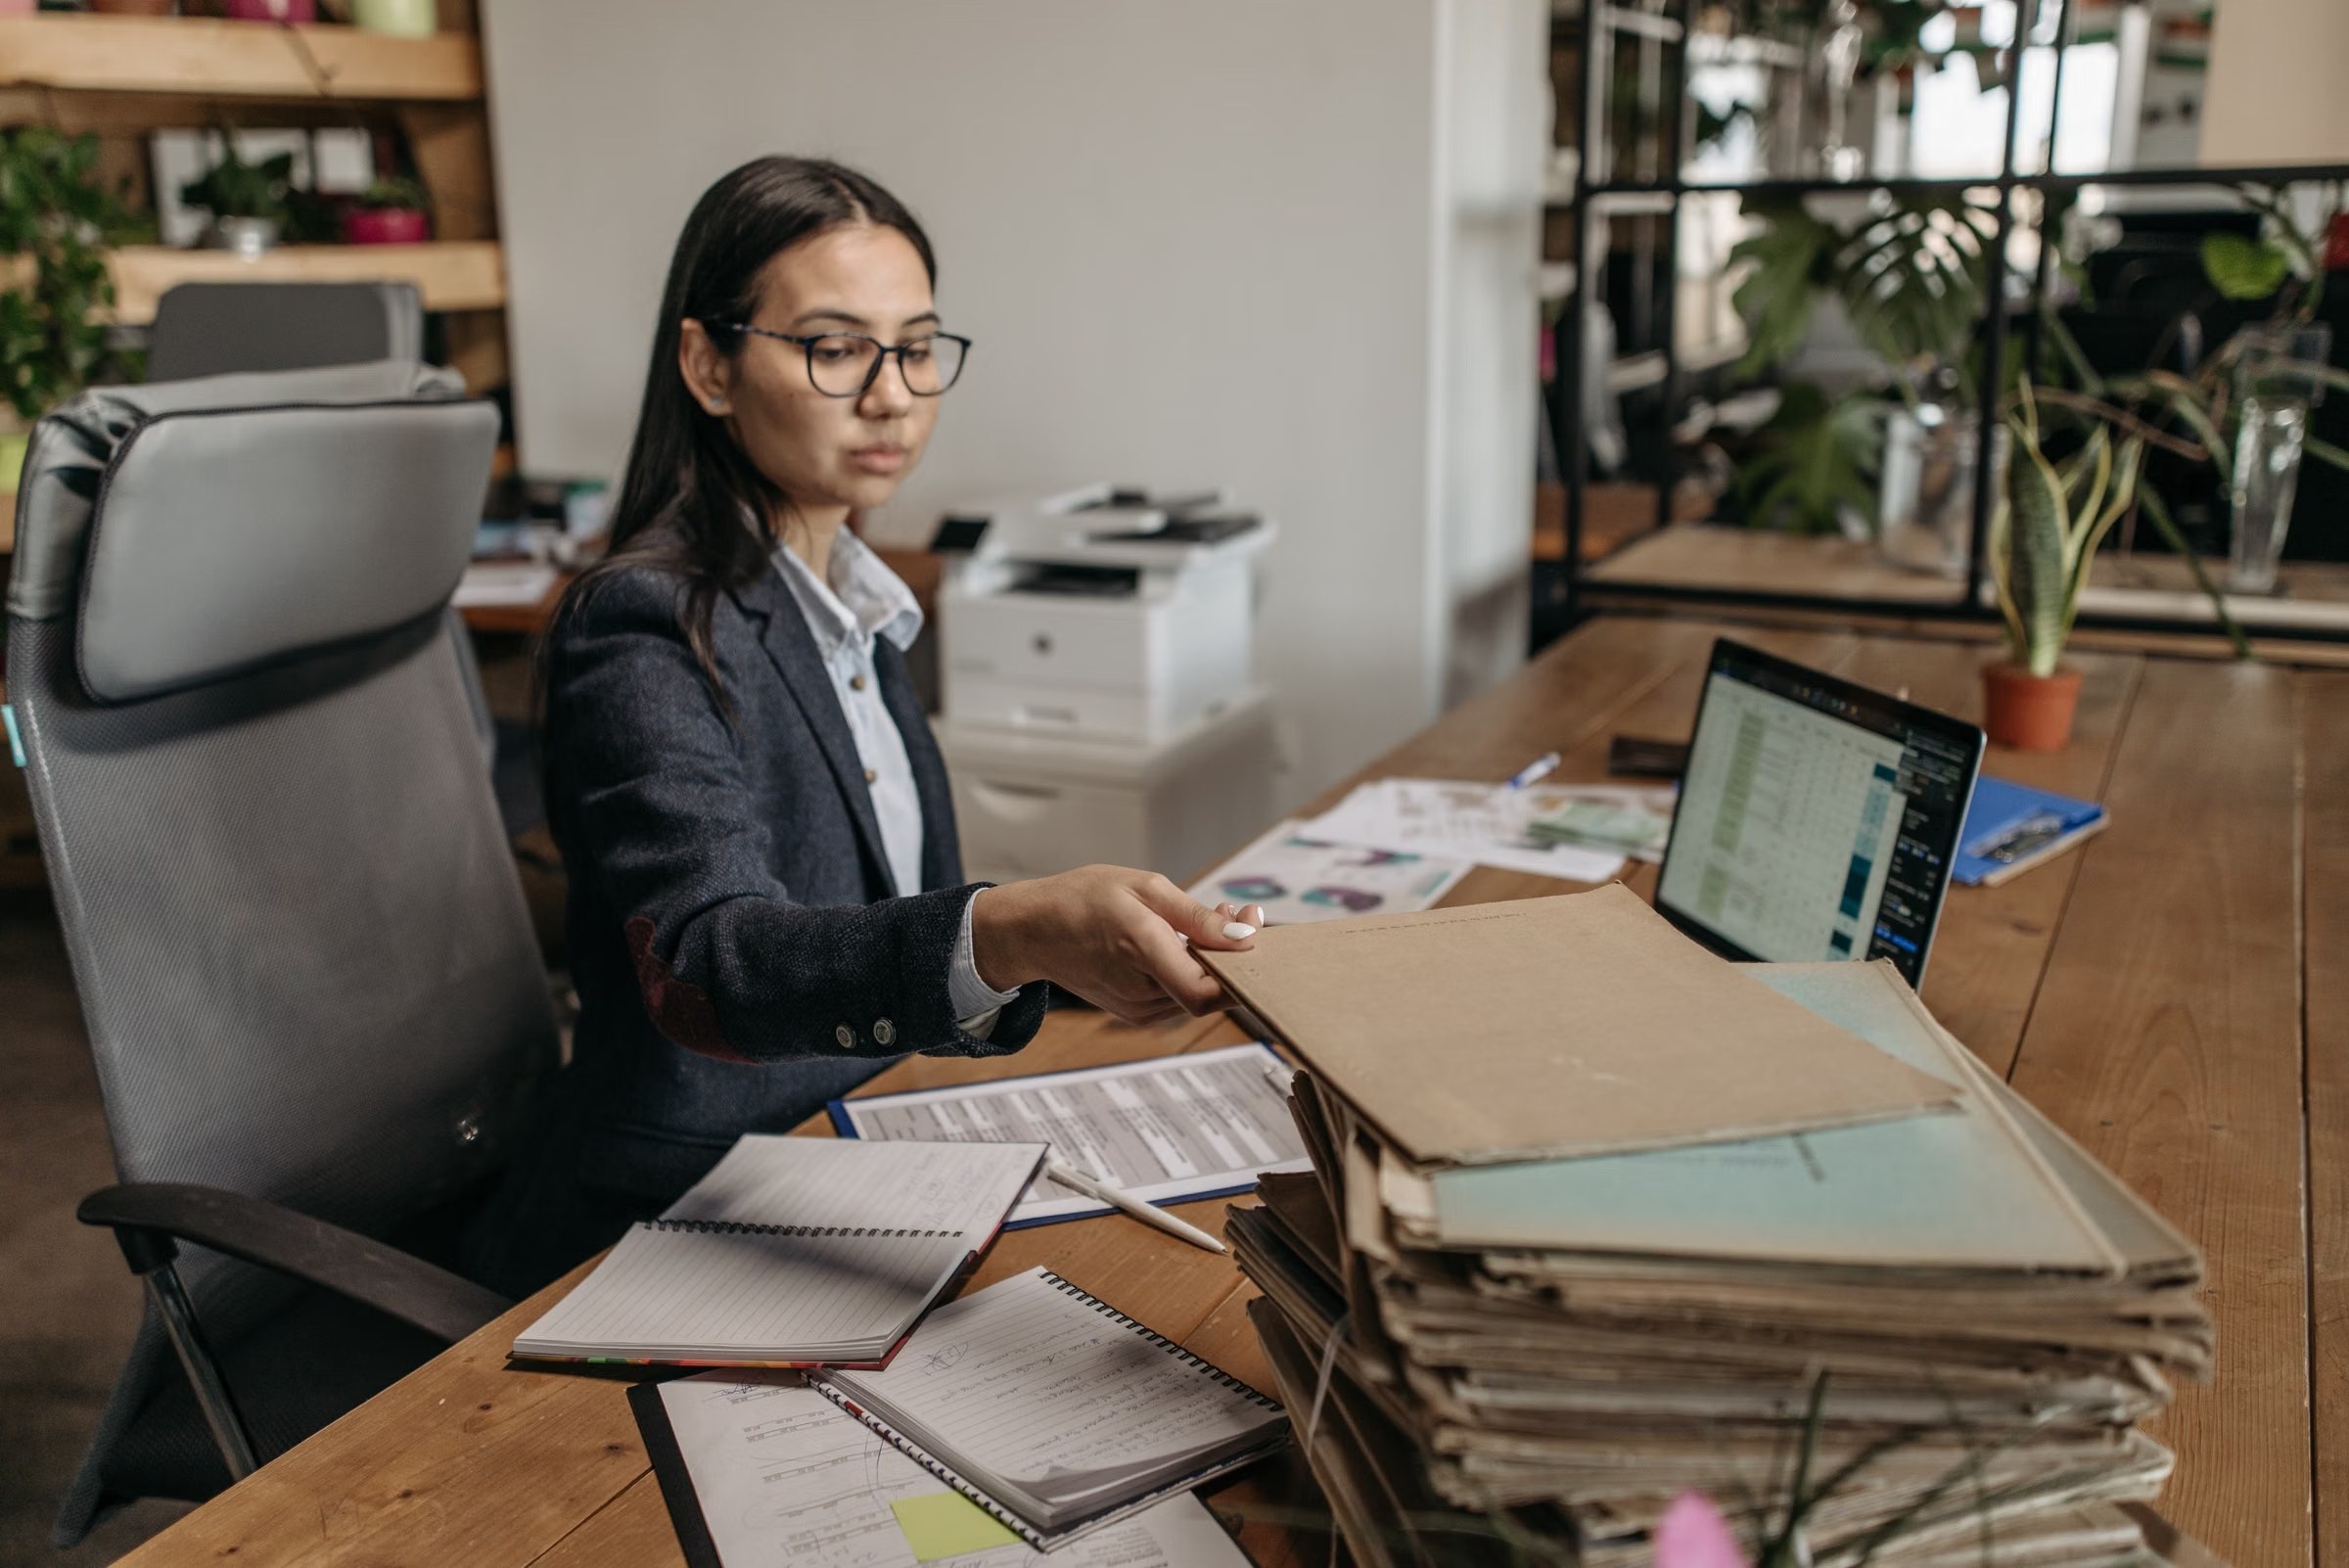
A reviewer reading papers at a desk alongside folders and a laptop.

Agreed-upon procedures

The parties agree which records to inspect, which comparisons to make and who will use the findings. The final report describes what each procedure found.

What to prepare
Identify the funding agreement or reporting condition, the proposed checks and the intended recipients. You can describe the documents before sharing them.
What it covers
A report of procedures and factual findings. The recipients draw their own conclusions. This engagement provides no audit opinion or assurance conclusion.